Cap rate vs. cash-on-cash: how to read a rental’s numbers
Two numbers, two different questions. One tells you about the property; the other tells you about your money. Here’s each one worked out on the same house.
When someone sends me a rental listing, the first question is usually “is this a good deal?” The honest answer is that it depends on which question you’re asking. Cap rate and cash-on-cash return both sound like “the return,” but they measure different things, and the same house can look fine on one and bad on the other.
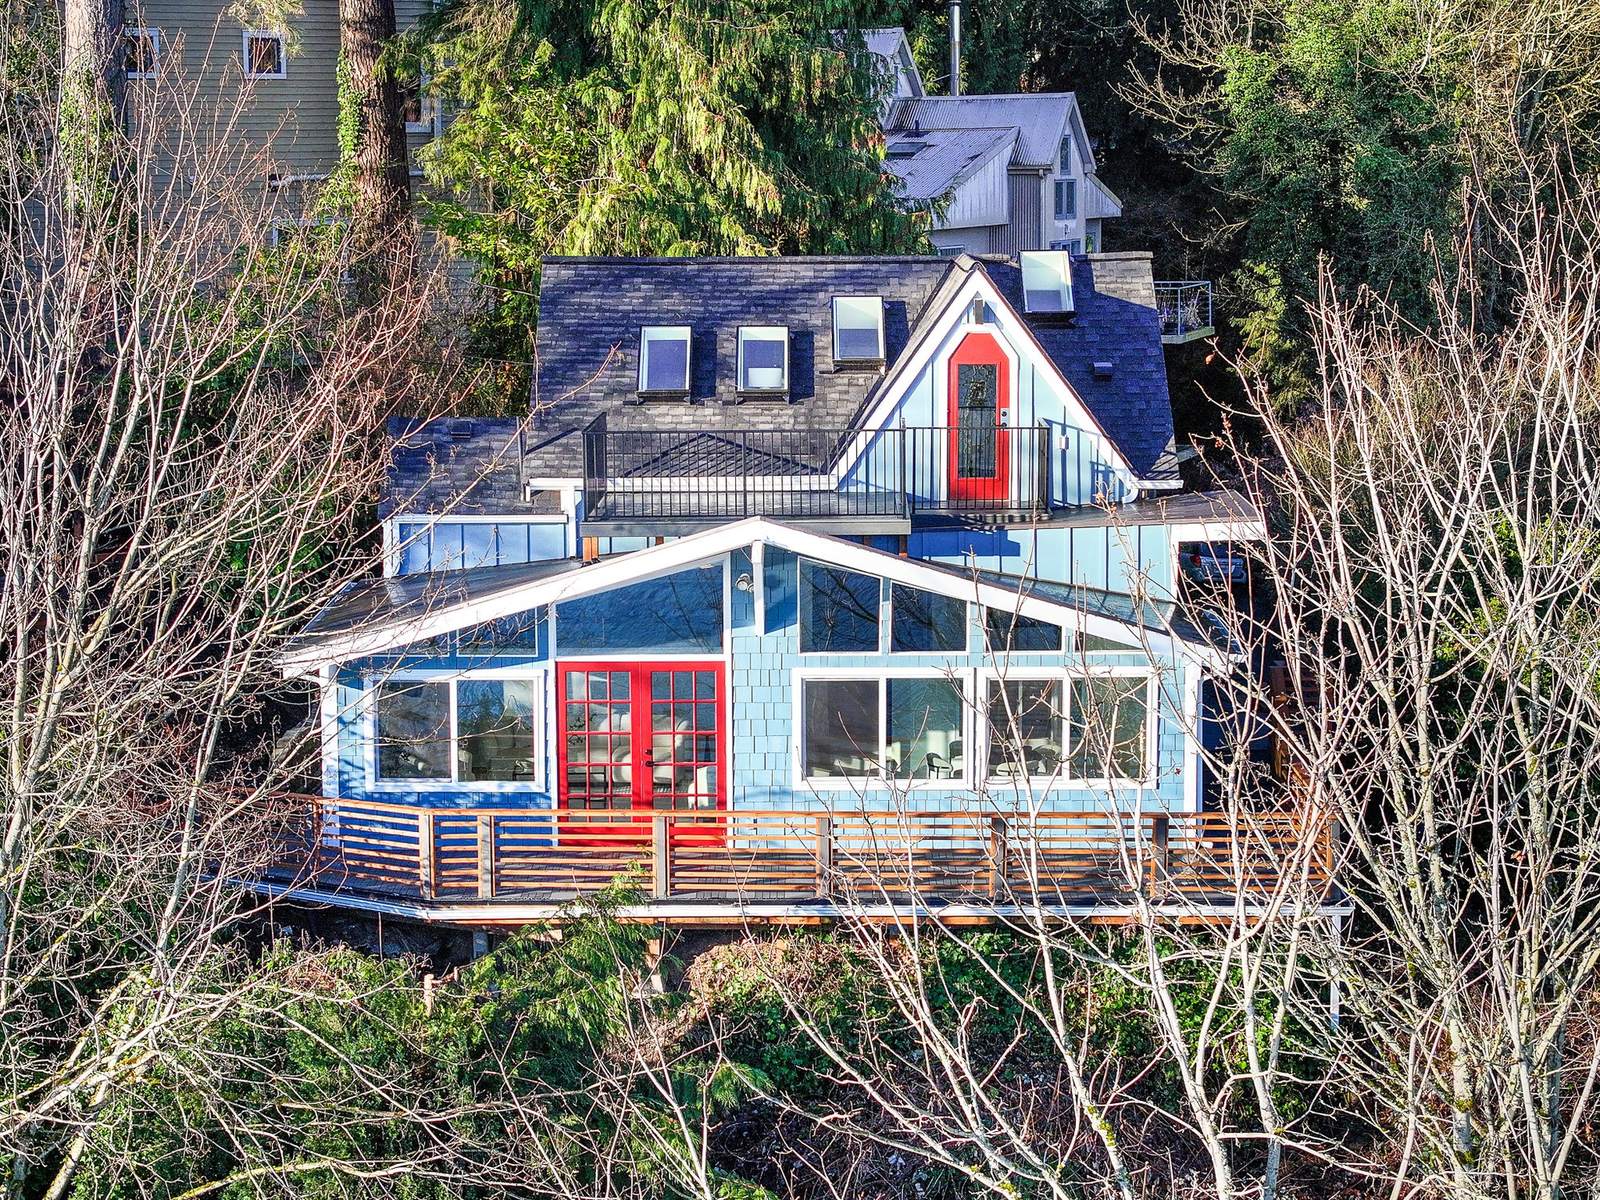
We’ll use one example the whole way through: a $600,000 house that rents for $3,400 a month. Round numbers, made up for illustration.
Cap rate: the property on its own
Cap rate is the property’s yearly net operating income (NOI) divided by its price. It ignores the mortgage entirely, as if you paid cash. That makes it the cleanest way to compare one property against another.
| Rent, $3,400 × 12 | $40,800 |
|---|---|
| Vacancy, 5% | −$2,040 |
| Maintenance and management, 8% each | −$6,528 |
| Property tax | −$5,400 |
| Insurance | −$1,400 |
| Net operating income | $25,432 |
| Cap rate, $25,432 ÷ $600,000 | 4.24% |
A 4.24% cap rate means the house, on its own, earns about four cents a year for every dollar of price. Whether that’s good depends on what else you could buy and what money costs right now.
Cash-on-cash: your money, with the loan
Cash-on-cash return is the cash the property puts in your pocket each year, after the mortgage, divided by the cash you put in to buy it. This is the number that tells you how your financing changes the picture.
| Down payment, 25% | $150,000 |
|---|---|
| Closing costs, about 3% | $18,000 |
| Cash you put in | $168,000 |
| Mortgage on $450,000, principal and interest | $2,918.69 a month |
| NOI per month, $25,432 ÷ 12 | $2,119.33 |
| Cash flow | −$799 a month, −$9,592 a year |
| Cash-on-cash, −$9,592 ÷ $168,000 | −5.7% |
Same house, and now it loses about $800 a month. Nothing about the property changed. The loan did that.
The part most people miss
When the loan costs more than the house earns
The mortgage payments add up to $35,024 a year on a $450,000 loan, which is about 7.8% of what you borrowed. The house only earns 4.24%. Borrowing money that costs more than the property returns is called negative leverage, and it pushes cash-on-cash below the cap rate. When the property earns more than the loan costs, it works the other way, and leverage lifts your return.
What would make this one work?
Keeping everything else the same:
- Higher rent. At about $4,410 a month, the house breaks even with this loan.
- More cash down. At 50% down ($318,000 in, with closing costs), cash flow turns slightly positive, about $174 a month, which is roughly a 0.7% cash-on-cash return.
- A different property. More rent for the price is what moves the cap rate, and no financing trick replaces that.
Cash-on-cash also leaves things out. In this example the loan balance drops by about $4,800 in year one, and any appreciation or tax benefits come on top of that. Those matter, but they don’t pay a monthly shortfall, so I look at them separately.
How I use them together
- Cap rate to compare properties against each other, apples to apples.
- Cash-on-cash to decide whether a property makes sense with your down payment and today’s rates.
- Both before we tour, so the numbers are real before anyone falls in love with a kitchen.
This is an illustration with made-up round numbers, not financial, tax or legal advice. Talk with your lender and a CPA before you buy an investment property.
Broker with Keller Williams PNW in Everett. I help people buy, sell and invest across Snohomish and King counties.
Text me a listing to look at